
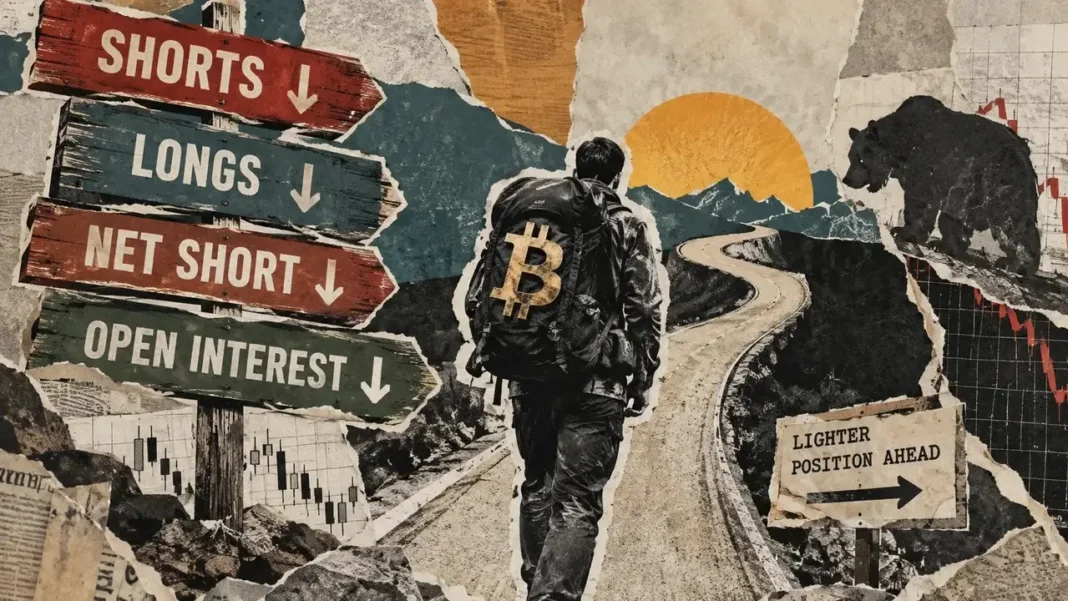

During the week leading up to Sept. 29, leveraged funds registered a decrease of approximately 5,300 BTC-equivalent in their reported Bitcoin futures shorts, which consequently reduced their net short position even as their total long exposure contracted.
The most recent futures-only figures from the Commodity Futures Trading Commission, published during the Oct. 2 reporting cycle, encompass CME standard and micro Bitcoin futures, alongside Coinbase Derivatives’ nano Bitcoin and nano perpetual-style futures. These totals translate various contract sizes into BTC-equivalent exposure, reflecting futures positions rather than physical bitcoin transfers.
When measured against positions from Sept. 22, the funds saw their reported shorts drop by 5,299.69 BTC-equivalent and their longs decline by 908.99 BTC-equivalent. As a result, their net short narrowed by 4,390.70 BTC-equivalent, moving from 40,110.83 to 35,720.13. Despite this shift, combined short exposure remained higher than long exposure. These long and short metrics do not include separately documented, offsetting spread positions.
A healthier net metric can emerge when positions on both sides decrease, provided that shorts decline at a faster rate. In this particular data snapshot, aggregate futures long exposure failed to grow.
Movement across individual products was mixed. Standard CME futures contributed 4,310 BTC-equivalent to the drop in reported shorts, while leveraged-fund longs in those contracts climbed by 1,175 BTC-equivalent. Conversely, longs decreased in CME micro futures and across both Coinbase offerings, overshadowing the aforementioned increase.
The shift in standard CME contracts reversed the expansion of net shorts observed in the Sept. 22 snapshot. While that earlier data release focused exclusively on standard CME, the latest aggregate metrics incorporate all four products.
Across all four products, asset managers’ net long positions grew by 2,137.90 BTC-equivalent to reach 18,069.10. Their long positions ticked up by 573.10 BTC-equivalent, while shorts dropped by 1,564.80 BTC-equivalent. Consequently, the bulk of their improved net standing was similarly driven by a decline in reported shorts.
Meanwhile, combined open interest—representing outstanding futures exposure across these tracked markets—dropped 13.31% from 119,208.26 to 103,343.14 BTC-equivalent. This enhancement in net positioning unfolded alongside a shrinkage in the broader futures market covered by the report.
Smaller shorts do not establish spot demand
The independently recorded spreading positions denote offsetting trades. The spreading column for leveraged funds also contracted, dropping by 11,231.11 BTC-equivalent. The 5,300 BTC-equivalent reduction is strictly tied to the reported short column and excludes those spread components.
The monthly CME micro expiry schedule placed the September expiry date on Sept. 25, falling right between the two observation points. While this offers helpful calendar context, it does not definitively prove that the expiry event or contract rolls triggered the contraction. Category totals can also be influenced by classification adjustments.
The CFTC categorizes market participants based on their primary business operations. Its Tuesday position reports do not disclose specific transactions, nor do they track paired spot and ETF holdings. Because a futures short may function as a hedge, a drop in short positions does not automatically confirm fresh spot buying or a weakening of bearish sentiment.
The following data release is slated for Oct. 9, which will indicate whether this category trend continues.
Frequently Asked Questions
-
What caused the narrowing of leveraged funds’ net short position?
The net short position narrowed because reported shorts fell faster than aggregate long exposure shrank during the week leading up to Sept. 29.
-
Which products are included in the CFTC futures figures?
The figures cover CME standard and micro Bitcoin futures, as well as Coinbase Derivatives’ nano Bitcoin and nano perpetual-style futures.
-
Does a reduction in futures shorts mean there is an increase in spot demand?
No. Because futures shorts can be part of hedging strategies and CFTC reports do not track spot or ETF holdings, fewer shorts do not prove fresh spot buying or a decline in bearish conviction.
-
When is the next CFTC futures report scheduled for release?
The next release is scheduled for Oct. 9.