

Standard Chartered anticipates that Ethena’s ENA token will climb roughly sevenfold by the year 2028, assuming the protocol successfully revitalizes its contracting synthetic-dollar operation.
The financial institution initiated its coverage of ENA with a year-end 2028 price target of $2, rising from its current valuation around $0.28. Its roadmap predicts the asset will hit $0.42 by the end of 2026 and $1.10 in 2027 before experiencing accelerated growth the year after.
Should this forecast hold true, ENA is set to outpace the bank’s projected performance for both Ethereum and Bitcoin over that same timeframe. However, achieving this milestone demands that Ethena reverse a recent downturn—which has shrunk USDe supply by more than half from its highest point—and scale far beyond any previous benchmarks.
The bank’s perspective relies on Ethena uncovering fresh yield avenues as returns from its foundational crypto trading approach dwindle. Simultaneously, it must pull in enough revenue from a vastly expanded USDe base to heighten the long-term utility and value of holding ENA.
Ethena first has to rebuild USDe
Following its late 2023 rollout, USDe quickly climbed to become one of the fastest-expanding stablecoins in the digital asset sector, surpassing $10 billion as users rushed into a strategy pairing spot crypto long holdings with perpetual futures short positions.
This design permitted Ethena to collect funding payments while maintaining a market exposure profile that stayed largely delta-neutral. On occasion, this tactic yielded returns exceeding 20%, driving capital deposits into both USDe and its yield-generating partner, sUSDe.
Nevertheless, those favorable market dynamics have since cooled during the subsequent market downturn.
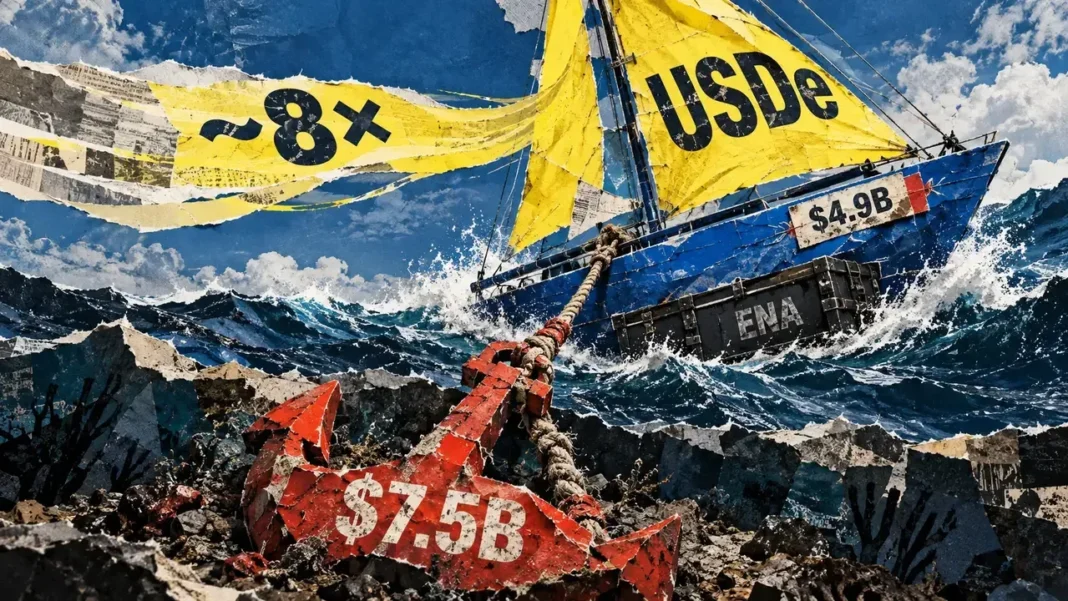
As the trade grew increasingly popular and crypto funding rates dropped, the total supply of USDe contracted to approximately $4.9 billion. Standard Chartered calculates that Ethena’s combined yield across all current strategies rests near 5.2%.
The bank’s model presupposes that this contraction can be dramatically reversed. It projects USDe supply to hit $40 billion by 2028, meaning Ethena must first recover its former $10 billion peak before quadrupling that figure once again.
In response to diminishing crypto basis returns, Ethena has sought out broader yield generation channels. Its current operations now encompass institutional lending, DeFi lending, real-world assets, and liquid stablecoins, along with newer basis trades tied directly to commodities and equities.
This ongoing diversification serves as a core pillar for Standard Chartered’s expansion hypotheses.
The bank estimates that tokenized assets—including real-world assets and stablecoins—will expand from roughly $350 billion today to approximately $4 trillion by the close of 2028. Furthermore, it forecasts that real-world assets integrated onto blockchains could surge from around $40 billion to $2 trillion within that same window.
A broader tokenized asset market would supply Ethena with enhanced collateral options and yield prospects independent of crypto derivatives, potentially enabling USDe to scale without relying on another era of exceptionally high perpetual-futures funding rates.
Additionally, Ethena is developing products outside of its central synthetic dollar, such as white-label stablecoins and Ethena Pay. Standard Chartered anticipates these ventures will broaden the protocol’s income streams as it scales.
Yet, the initial milestone sits much closer than the $40 billion mark.
Ethena’s approved fee-switch mechanism activates at a $7.5 billion USDe supply threshold, placing the protocol below the initial baseline required for the revenue mechanism underpinning Standard Chartered’s valuation model to engage.
Why the buyback math leads to $2
Once those milestones are cleared, the valuation of ENA becomes increasingly tied to how effectively Ethena can channel its underlying economics toward token holders.
The sanctioned framework designates 95% of eligible net revenue—paid to the Ethena Foundation via covered operations—toward ENA buyback initiatives. Because Ethena does not retain 100% of the yield produced by the collateral supporting USDe, the distinction separating gross revenue from net revenue remains critical to the equation.
An analysis by Blockworks Advisory simulated the protocol’s portion of gross revenue scaling alongside USDe supply, starting at roughly 5% at the $7.5 billion mark and expanding to 20% when reaching $20 billion. This model applied a 6% protocol yield simply as an illustrative figure rather than a guaranteed payout.
At the massive scale envisioned by Standard Chartered, these economic parameters grow substantially.
The banking institution estimates that if USDe hits the $40 billion threshold, annual ENA buybacks could account for nearly 23% of the token’s current market capitalization, assuming its price stayed static.
However, Standard Chartered does not anticipate such a high percentage will be sustained over time. It posits that investors would naturally price this anticipated stream of buybacks directly into ENA’s valuation, driving the token’s price upward and lowering the annual buyback ratio relative to its overall market cap.
As a historical parallel, the bank references Uniswap, noting that UNI’s annualized buyback percentage stabilized between 3% and 4% following the activation of its fee switch as the token appreciated. Projecting a comparable equilibrium onto Ethena supports Standard Chartered’s $2 price goal.
Even so, this mechanism introduces internal structural challenges.
Securing a larger portion of Ethena’s revenue for the protocol itself can diminish the returns left over for sUSDe participants. This establishes a delicate balancing act: Ethena must preserve enough margin to fund ENA buybacks while maintaining yield offerings competitive enough to continually attract the inflows necessary for USDe expansion.
These core assumptions grow progressively demanding as supply climbs. The 6% baseline return utilized in the framework lacks a guarantee across varied market cycles, and the elevated revenue-sharing tiers have yet to undergo real-world testing at the magnitude Standard Chartered projects.
Consequently, investors face several immediate milestones before the $2 projection becomes actionable. USDe must first surpass the $7.5 billion fee-switch trigger and recover its past peak supply.
Beyond those benchmarks, Ethena must prove that its newer yield ventures can absorb tens of billions of dollars cleanly without severely compressing returns. The speed at which these hurdles are cleared will dictate whether Standard Chartered’s envisioned buyback engine mirrors the model integrated into its financial valuations.
Frequently Asked Questions
What is Standard Chartered’s price target for ENA?
Standard Chartered initiated coverage with a year-end 2028 price target of $2 for Ethena’s ENA token, up from around $0.28.
What needs to happen for Ethena to reach the bank’s target?
Ethena must rebuild its contracting USDe supply, growing it from a recent low of about $4.9 billion up to $40 billion by 2028, while also successfully utilizing new yield strategies.
How do ENA buybacks work under the protocol’s framework?
The approved framework allocates 95% of qualifying net revenue paid to the Ethena Foundation from covered businesses toward ENA buybacks once the USDe supply crosses the initial $7.5 billion threshold.
How does Ethena generate its yield?
Ethena originally relied on a strategy combining long spot crypto positions with short perpetual futures, but it has since broadened its methods to include DeFi lending, institutional lending, liquid stablecoins, real-world assets, and equity/commodity basis trades.